What Is Medical Insurance in Hong Kong
Product documents checked 21 October 2026
For most people considering private hospital treatment, indemnity hospital insurance is the starting point. It helps pay eligible bills within the contract. Hospital cash and critical illness cover serve different purposes.
Three terms that are easy to mix up
| Product or benefit | How it pays | What it does not establish |
|---|---|---|
| Hospital indemnity insurance | Reimburses eligible hospital and related medical expenses | That every billed item will be paid in full |
| Outpatient reimbursement | Pays eligible consultation, medicine or test costs within limits | That all providers or services qualify |
| Hospital cash | Pays a stated amount for qualifying days or events | That the actual hospital bill will be reimbursed |
A fixed hospital-cash benefit can be payable alongside expense reimbursement when its own conditions are met. The rule against receiving more than the same medical expenses applies to coordinating indemnity reimbursements, not to treating every cash benefit as reimbursement.
Where VHIS fits
The Voluntary Health Insurance Scheme is a Hong Kong certification framework for individual hospital insurance. The government sets requirements; insurers issue policies, underwrite applications and assess claims.
Standard Plans follow the scheme's basic structure. Flexi Plans build on it. “High-end” is a market description rather than a third official certification type; such a plan can be a Flexi Plan with broader benefits and a different reimbursement structure. [S24]
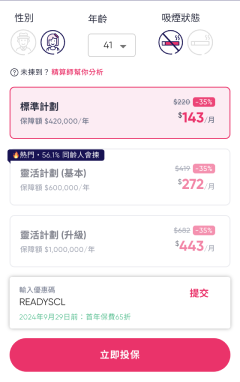
Bowtie offers Standard, Flexi Regular and Plus, and Pink room tiers. Compare the actual benefit schedules rather than assuming the product name tells you the size of a possible payout.
Six parts of a hospital policy to read
The eligible services
Hospital stays, day-case procedures, scans and cancer treatment have different benefit conditions. A doctor's recommendation helps explain the treatment, but does not override exclusions or every element of medical necessity.
Item limits
A plan may have a large annual limit and a much smaller surgeon's-fee or miscellaneous limit. Standard's annual basic limit is HK$420,000, but its miscellaneous allowance is HK$14,000 per year. [S2]
Deductible and coinsurance
A deductible is an amount you bear before the relevant insurance payment; coinsurance is a percentage contribution. Check the unit: Pink uses an annual deductible, not a fresh deductible for every operation. [S11]
Renewal and premium revisions
Guaranteed renewal protects continued cover under the terms. It does not freeze the premium. Your age-rated premium can change and the product's rate schedule can be revised on the permitted basis. [S1]
Territory and room restrictions
Check the exact hospital, country and room you intend to use. A room upgrade can reduce more than the room-charge benefit, and an overseas provision can change the benefit level.
Personal underwriting terms
Read your schedule and endorsements. A standard brochure does not show a personal exclusion or loading added to your own policy.
A simple bill calculation
The following is hypothetical, not a quoted plan. Suppose an eligible HK$100,000 bill includes HK$2,000 above a room limit. Assume the remaining HK$98,000 qualifies, there is a HK$20,000 deductible and no other adjustments.
The insurer would pay HK$78,000 under those assumptions. The patient would pay HK$22,000: the deductible plus the amount above the room limit.
An SMM benefit would not automatically pay the HK$2,000 room excess. Its eligibility list must include the relevant item; Bowtie Flexi's SMM does not operate as a general supplement to every room charge. [S5]
Public healthcare remains an option
Having private insurance does not stop an eligible person using public care. Hospital Authority eligibility and fees follow their own rules. Insurance primarily changes how you can fund eligible private treatment and the choices you may have over timing, doctor and room. [S25]
If you are deciding whether cover is useful, think about which care route you would actually choose and what you could pay after the policy's limits. Avoid comparing a private bill with only the headline annual insurance limit.
Start with the cover you already have
Obtain your company benefits schedule and any existing personal policies. Note what continues when you leave work and whether family members are included.
Then choose what gap you want to address. For example, a personal plan with a deductible may supplement company benefits, but you need savings for the deductible if that company cover ends. Do not cancel existing personal cover until you understand a new policy's underwriting decision.
Related reading
What is VHIS? · Do I need VHIS? · Medical vs critical illness cover
Sources and method
Published documents checked 21 October 2026. Calculations are explained in the article; hypothetical examples are not customer claims. The applicable policy and underwriting terms govern individual cover.
[S1] Bowtie VHIS Standard — Terms and Conditions
[S2] Bowtie VHIS Standard — Standard – Benefit Schedule
[S5] Bowtie VHIS Flexi — Flexi Regular – Benefit Schedule
[S11] Bowtie Pink — Supplement No. 1-3
[S24] VHIS Office — scheme requirements and consumer questions
[S25] Hospital Authority — fees and eligible-person rules
General information only. Coverage, exclusions and payment are governed by the applicable policy terms. This article does not replace individual insurance, medical or tax advice.
