Medical Insurance vs Critical Illness vs Life Insurance
Product documents checked 21 October 2026
The useful question is not which type is best. It is which unpaid bill, loss of income or family obligation you could not manage with your existing cover and savings.
Three jobs to distinguish
| Cover | What usually triggers payment | Main financial purpose |
|---|---|---|
| Indemnity medical insurance, including VHIS | Eligible medical expenses under the policy | Help pay treatment bills |
| Critical illness insurance | A covered illness satisfying its definition and other claim conditions | Provide money that can support recovery and living costs |
| Life insurance | A valid death claim during the cover period | Support dependants or meet debts and other obligations |
Medical reimbursement is limited by the expenses incurred and the policy. A critical illness lump sum does not normally depend on the amount of the hospital bill. A death benefit serves another purpose again.
Some products add early-stage, terminal illness or multiple-claim benefits. Read those provisions separately instead of treating every policy in the same category as identical.
What VHIS contributes
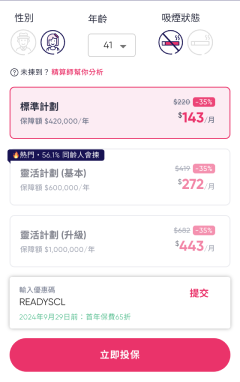
Hong Kong's Voluntary Health Insurance Scheme sets certification requirements for individual hospital insurance. Bowtie's Standard Plan has an annual basic benefit limit of HK$420,000, with individual limits for items such as surgery, diagnostic imaging and psychiatric treatment. A large annual limit does not remove those item limits. [S2]
Flexi Plans build on the Standard Plan framework. Some increase item limits or add Supplementary Major Medical benefits. High-end Flexi Plans may instead provide full reimbursement for designated items, subject to deductibles, annual and lifetime limits and other terms. [S24]
Hospital-expense reimbursement does not replace earnings while you cannot work. Any separate cash or incapacity benefits have their own triggers and limits. Nor does it pay every expense associated with illness: travel, childcare and some non-covered care may still come from savings or other protection.
What a critical illness diagnosis does and does not establish
A diagnosis alone is not enough to assume a claim will succeed. The condition must meet the contract's definition; waiting periods, survival requirements and other conditions may also apply depending on the product.
For example, “cancer cover” can mean different things for early-stage disease, carcinoma in situ and invasive cancer. The number of illnesses advertised is less useful than understanding the definitions and payment amounts for the risks you are trying to cover.
Ask for the actual policy wording. If you want to use the payment to replace income, estimate essential monthly spending, expected time away from work and the savings already available.
One illness can create two separate needs
Consider a hypothetical person whose eligible treatment bill is HK$300,000. Suppose medical insurance reimburses HK$260,000 after applying its limits. The HK$40,000 gap is one problem. Six months without earnings is another.
If a separate critical illness policy pays a valid HK$500,000 lump sum, that money could meet the gap and living costs. This is an illustration of different benefit types, not a promised payout or a recommendation to buy that amount.
A life policy would not normally pay a death benefit while the insured person is alive. Any living benefit would need its own claim conditions to be met.
Decide priorities from your actual circumstances
A young worker with strong company medical cover, no dependants and limited savings may have different priorities from a parent with a mortgage. Age alone cannot settle the order.
Start with these three figures:
- The treatment cost you would have to fund after existing medical benefits.
- Essential household spending during a period without earnings.
- Debts and ongoing support that would remain if you died.
Then review company benefits. Group medical or life cover may end with employment, and the amounts may not match your family's needs. If you already hold a personal policy, compare its existing terms before buying overlapping cover.
Where money is tight, compare a smaller amount of useful protection with keeping an emergency reserve. A policy with a deductible you cannot afford may leave an immediate problem even if its premium looks attractive.
How tax fits into the decision
Qualifying VHIS premiums may be deducted for salaries tax or personal assessment, subject to eligibility and the HK$8,000 cap per taxpayer for each insured person in a year of assessment. A deduction reduces taxable income; it is not an HK$8,000 tax refund. [S22]
Ordinary critical illness and life insurance premiums do not qualify for the VHIS deduction. That is a statement about this medical-insurance relief, not a claim that no other insurance product can receive any tax relief.
Questions to ask before choosing
Ask which event triggers payment, whether the benefit reimburses expenses or pays a fixed amount, how long cover lasts, and whether premiums can change. For medical cover, inspect item limits; for critical illness cover, inspect definitions; for life cover, inspect the benefit, term and beneficiary arrangements.
Related reading
VHIS coverage · Company medical top-ups · VHIS tax deduction
Sources and method
Published documents checked 21 October 2026. Calculations are explained in the article; hypothetical examples are not customer claims. The applicable policy and underwriting terms govern individual cover.
[S1] Bowtie VHIS Standard — Terms and Conditions
[S2] Bowtie VHIS Standard — Standard – Benefit Schedule
[S24] VHIS Office — scheme requirements and consumer questions
[S22] Inland Revenue Department — VHIS deduction questions
General information only. Coverage, exclusions and payment are governed by the applicable policy terms. This article does not replace individual insurance, medical or tax advice.
