

 VHIS
 GHK Wellness Package


 Group Medical Insurance


 中
Best Value Premiums in Town¹


Before you buy, see what our Product Lead has to say!
Affordable Coverage – Built for the Long Term
Best value in town¹
Save 36% on Premiums on Average
Great Value for 30 Years

1Based on a market survey conducted by Bowtie on March 17, 2026, comparing 7 similar high-end Voluntary Health Insurance Schemes (VHIS) in the market that feature online application, full reimbursement, semi-private room level, $0 deductible, and the same coverage area. The total premiums of Bowtie Pink for non-smoking males aged 35 to 64 are all lower, calculated based on the average value of the total premiums. The coverage and benefit limits vary across different medical insurance plans; for details, please refer to the relevant insurance policies and their terms and conditions. The calculated premiums above are for reference only. The actual premium you need to pay is subject to factors such as time, inflation, and underwriting, and is subject to the premium levy collected by the Insurance Authority.
Straightforward claims — we won't use fine print to reject your claim⁺
98.3% claims approval rate, ahead of the industry^
What makes our claims service work so well?

One-to-one support from a Claims Specialist
Support until 3am. Median claims assessment time: 6 working days3
Service hours: Monday to Friday, 9:30am to 3am the following day
(excluding public holidays)
24-hour worldwide emergency assistance4 ↗
Cover when you travel or move abroad, subject to policy terms5
Available at all private hospitals in Hong Kong
 Warren | Product Specialist
F
U

L
L
Full reimbursement
for eligible medical expenses2
Annual benefit limit: up to $20 million (resets each policy year)
Lifetime benefit limit: up to $80 million
No itemised benefit limits, with full reimbursement² for eligible medical expenses including diagnosis, hospitalisation, surgery and prescribed non-surgical cancer treatments, so you can worry less about shortfalls! Deductibles, annual and lifetime benefit limits, and policy terms apply.
What’s a deductible? How does it work?
A deductible is the amount you need to pay by yourself in the event of a claim before the insurance company pays for your eligible medical expenses. The insurance company would cover any remaining medical expenses according to the benefit limits in the policy. The deductible of Bowtie Pink is counted per policy year.
How to choose deductible?
Save your premium with the right deductible
You have 4 deductible options. Pick a deductible that fits your medical and financial needs. The higher a plan's deductible is, the lower the premium will be.
What type of room do you prefer?
 Group medical


💡 Tight budget? Get Bowtie VHIS - Flexi Plan for just HK$254/month
Group medical
room and board coverage
less than $600less than $1,500less than $4,300
Recommend this if you are not sure of your coverage
Group medical
room and board coverage
$600 - $800$1,500 – $1,800$4,300 – $5,300
Group medical
room and board coverage
more than $800more than $1,800more than $5,300
*The above suggestions are for reference only and do not guarantee that there will be no out-of-pocket medical expenses. The above room and board costs are based on the market median (HK$4,129 per day for private rooms and HK$1,424 per day for semi-private rooms) published by the Hong Kong Federation of Insurers in the Medical Expenses Survey Report 2019 and are based on an estimated annual medical inflation rate of 5% until 2022. The reference range is 10% above and below the median. The above premium is based on 30-year-old non-smoker male, with deduction option HK$80,000.
Which to use first for making a claim if you have both group medical and Bowtie Pink?
Suggested practice:
- Submit the initial claim with your existing medical plan that has no deductibles (i.e. your company’s group medical plan/ personal medical plan)
- Submit a claim for the remaining expenses with Bowtie Pink
The benefit is that you can use the reimbursements from the existing medical plan to offset Bowtie Pink’s deductible to reduce any out-of-pocket payments.
How Bowtie can help if you can't afford the deductible after retirement?
Each Bowtie Pink VHIS policyholder can exercise a one-off right to reduce or remove the deductible, without re-underwriting and providing further evidence of the insurability of the insured.
Starting from 30 April 2023, where the Insured Person has been covered under the Policy continuously for 2 consecutive Policy Years. Subject to the Deductible options available at that time, the policyholder can request to exercise such right, made not less than 30 days prior to the Renewal Date on or immediately following the date that the Insured Person attains the Age of 55, 60, 65, 70, 75 or 80.
In any case, after the change of Deductible, the premiums of the Policy willbe adjusted according to the prevailing Standard Premium schedule and the relevant Terms. For details, please refer to the policy terms and conditions Supplement No. 1.
Not sure which deductible option is right for you?
Call 3008 8123, we’re here to help.
Full reimbursement for eligible medical expenses2
Full reimbursement for eligible hospital, surgical and treatment expenses
💯 Full reimbursement of eligible expenses²
Diagnosis and tests

- CT, MRI and PET scans (prescribed diagnostic imaging tests) 💯
- Outpatient or emergency consultations before hospitalisation or day surgery (excluding routine consultations for colds and flu)
- Emergency outpatient treatment for accidents
- Complimentary BowtieGo membership: unlimited outpatient visits at up to 50% off⁷
Hospitalisation

- Room and board 💯
- Attending doctor's visit fees 💯
- Specialist's fees 💯
- Targeted therapy, chemotherapy, radiotherapy and proton therapy, among others (non-surgical cancer treatments) 💯
- Psychiatric treatment 💯
- Companion bed charges 💯
- Intensive care (ICU) 💯
- Miscellaneous hospital charges 💯
Day surgery / inpatient surgery

- Surgeon's fees 💯
- Anaesthetist's fees 💯
- Operating theatre charges 💯
- Day surgery cash benefit
Follow-up care
- Follow-up consultations after discharge or surgery (including specialist consultations and physiotherapy) 💯
- Dialysis (outpatient kidney dialysis) 💯
- Rehabilitative care
- Daily home nursing charges after discharge
No need to add Cancer Fighter!
Bowtie Pink already provides full reimbursement for eligible cancer-related hospitalisation, surgery and non-surgical treatments (such as radiotherapy, chemotherapy, targeted therapy, immunotherapy and hormonal therapy).
Real claim examples, comprehensive coverage of illnesses
Below are 10 common claims examples, covering medical conditions and medical expenses of varying severity. You can use them to compare plan payout rates and choose the Bowtie VHIS plan that best fits your needs and budget.
Upgrade options for semi-private and private rooms
$40,000,000 per lifetime
$50,000,000 per lifetime
$80,000,000 per lifetime

Want to explore other VHIS plans?
Trusted by Real Customers: 4.6 ⭐ on Google
Why You Can Trust Bowtie
Total Customers
150,000+


FT High-Growth Companies Asia-Pacific 2026#
Gabriel Kung, Chief Commercial Officer
Total Funding Raised
HK$1.2 Billion


Michael Chan, CEO & Co-Founder of Bowtie Clement Lam, CEO of Sun Life Hong Kong Limited and Non-Executive Director of Bowtie Fred Ngan, Co-Founder of Bowtie (from left to right)
5 Consecutive Years of Hong Kong Sales Leadership
No.1

No.1 in Number of Direct Business Policies Q1 2025, 2021–2024*
John Tsang, Senior Advisor
#Based on the “FT High-Growth Companies Asia-Pacific” rankings jointly compiled by the Financial Times and Statista for 2 consecutive years (2025 and 2026), where Bowtie ranked No.1 among shortlisted Hong Kong companies in revenue growth. *According to the provisional statistics on long term insurance business released by the Insurance Authority, Bowtie Life Insurance ranked the highest in Hong Kong in terms of the number of new individual non-single premium policies sold through direct marketing channels from 2021 to 2024 annually, and in the first quarter of 2025.
Medical insurance with extra health benefits
Earn 8% in BowtieCash after 6 months without a claim Use it towards eligible medical costs your plan doesn't fully cover8
Learn more →
Automatic coverage upgrades for 7 consecutive years
Learn more → Jacky | Chief Medical Officer
Unlimited outpatient visits at up to 50% off
Learn more →
Important product information
- Eligible for persons aged 15 days to age 80
- Covers
unknown pre-existing conditions and congenital diseases - No waiting periodlevel up!Excluding Unknown Pre-existing Conditionsenjoy 100% reimbursement starting from the 91st day from the effective date of the policy. Terms Explained → (Chinese only)
- Lifetime guaranteed renewal
- Worldwide coverage (including immigration and travel)5Except for U.S. and non-designated Chinese hospitalsPsychiatric treatments only available in Hong Kong
- Monthly payment
Have pre-existing conditions? Does Bowtie cover you? Fill in a simplified questionnaire to see preliminary results for 39 common medical conditions at a glance
Results are for reference only; final underwriting results depend on full health declaration

Product documents

Benefit Schedule (including Surgical Schedule)
Ward
Benefit Schedule (including Surgical Schedule)
Semi-Private
Benefit Schedule (including Surgical Schedule)
Private
Renewal
- Upon renewal, there shall be no re-underwriting. No additional rate of premium loading or case-based exclusions shall be imposed by reason of any change in the Insured Person's health conditions.
- Upon renewal, we reserve the right to revise Policy Terms and Conditions, including the prevailing standard premium schedule, subject to prior approval by Health Bureau.
Policy cancellation
You may request cancellation of the plan by giving at least 30 days prior notice.
Cooling-off period
21 days. Within the cooling-off period, you may cancel the plan and receive a full refund of the premium.
Tax deduction
Taxpayers who purchase any Certified Plan of VHIS for him/herself or any specified family members are eligible for tax deductions. For details https://www.vhis.gov.hk/en/consumer_corner/tax-deduction.htm
Key exclusions
Under this plan, Bowtie will not pay any benefit in relation to or arising from the following:
- Treatments, procedures, medications, tests or services which are not Medically Necessary;
- Confinement solely for the purpose of diagnostic procedures or allied health services, unless such procedure or service is recommended by a Registered Medical Practitioner for Medically Necessary investigation or treatment of a Disability which cannot be effectively performed in a setting for providing Medical Services to a Day Patient;
- Treatment of Human Immunodeficiency Virus ("HIV") and its related disability, which is contracted or occurs before the Policy Effective Date. If evidence of proof as to the time eat which such Disability is first contracted or occurs is not available, manifestation of such Disability within the first 5 years after the Policy Effective Date shall be presumed to be contracted or occur before the Policy Effective Date (except cases where HIV and its related disability is caused by sexual assault, medical assistance, organ transplant, blood transfusions or blood donation, or infection at birth)
- Dependence, overdose or influence of drugs, alcohol, narcotics or similar drugs or agents;
- Self-inflicted injuries or attempted suicide, illegal activity, or venereal and sexually transmitted disease or its sequelae;
- Beautification or cosmetic purposes, unless necessitated by injury caused by an Accident and the Insured Person receives the Medical Services within 90 days of the Accident;
- Correction of visual acuity or refractive errors that can be corrected by fitting of spectacles or contact lens;
- Prophylactic treatment or preventive care (except treatments, monitoring, investigation or procedures with the purpose of avoiding complications, removal of pre-malignant conditions, and prevention of recurrence of complication);
- Dental treatment and oral and maxillofacial procedures performed by a dentist (except for emergency treatment and surgery during Confinement arising from an Accident);
- Medical Services and counselling services relating to maternity conditions and its complications or sexual dysfunction;
- Purchase of durable medical equipment or appliances;
- Traditional Chinese medicine treatment;
- Experimental or unproven medical technology or procedure in accordance with the common standard, or not approved by the recognised authority, in the locality where the treatment, procedure, test or service is received;
- Congenital Conditions which have manifested or been diagnosed before the Insured Person attained the age of 8;
- Treatment for Disability arising from war, civil war, invasion, acts of foreign enemies, hostilities, rebellion, revolution, insurrection, or military or usurped power; or
- Reimbursements under any law, or medical program or insurance policy provided by any government, company or other third party.
The above list is for reference only. You should refer to the "General Exclusions" section in the Terms and Conditions of this plan for the complete list and details of exclusions.
Bowtie VHIS registration info
Name of VHIS certified plan: Bowtie Pink VHIS Plan
Available for new application
- F00060-09-000-04 (Ward room - Deductible HK$0)
- F00060-10-000-04 (Ward room - Deductible HK$20,000)
- F00060-11-000-04 (Ward room - Deductible HK$50,000)
- F00060-12-000-04 (Ward room - Deductible HK$80,000)
- F00060-01-000-07 (Semi-Private room - Deductible HK$0)
- F00060-02-000-07 (Semi-Private room - Deductible HK$20,000)
- F00060-03-000-07 (Semi-Private room - Deductible HK$50,000)
- F00060-04-000-07 (Semi-Private room - Deductible HK$80,000)
- F00060-05-000-07 (Private room - Deductible HK$0)
- F00060-06-000-07 (Private room - Deductible HK$20,000)
- F00060-07-000-07 (Private room - Deductible HK$50,000)
- F00060-08-000-07 (Private room - Deductible HK$80,000)
Not available for new application (60 legacy codes)
- F00060-09-000-03 (Ward room - Deductible HK$0)
- F00060-10-000-03 (Ward room - Deductible HK$20,000)
- F00060-11-000-03 (Ward room - Deductible HK$50,000)
- F00060-12-000-03 (Ward room - Deductible HK$80,000)
- F00060-01-000-06 (Semi-Private room - Deductible HK$0)
- F00060-02-000-06 (Semi-Private room - Deductible HK$20,000)
- F00060-03-000-06 (Semi-Private room - Deductible HK$50,000)
- F00060-04-000-06 (Semi-Private room - Deductible HK$80,000)
- F00060-05-000-06 (Private room - Deductible HK$0)
- F00060-06-000-06 (Private room - Deductible HK$20,000)
- F00060-07-000-06 (Private room - Deductible HK$50,000)
- F00060-08-000-06 (Private room - Deductible HK$80,000)
- F00060-09-000-02 (Ward room - Deductible HK$0)
- F00060-10-000-02 (Ward room - Deductible HK$20,000)
- F00060-11-000-02 (Ward room - Deductible HK$50,000)
- F00060-12-000-02 (Ward room - Deductible HK$80,000)
- F00060-01-000-05 (Semi-Private room - Deductible HK$0)
- F00060-02-000-05 (Semi-Private room - Deductible HK$20,000)
- F00060-03-000-05 (Semi-Private room - Deductible HK$50,000)
- F00060-04-000-05 (Semi-Private room - Deductible HK$80,000)
- F00060-05-000-05 (Private room - Deductible HK$0)
- F00060-06-000-05 (Private room - Deductible HK$20,000)
- F00060-07-000-05 (Private room - Deductible HK$50,000)
- F00060-08-000-05 (Private room - Deductible HK$80,000)
- F00060-09-000-01 (Ward room - Deductible HK$0)
- F00060-10-000-01 (Ward room - Deductible HK$20,000)
- F00060-11-000-01 (Ward room - Deductible HK$50,000)
- F00060-12-000-01 (Ward room - Deductible HK$80,000)
- F00060-01-000-04 (Semi-Private room - Deductible HK$0)
- F00060-02-000-04 (Semi-Private room - Deductible HK$20,000)
- F00060-03-000-04 (Semi-Private room - Deductible HK$50,000)
- F00060-04-000-04 (Semi-Private room - Deductible HK$80,000)
- F00060-05-000-04 (Private room - Deductible HK$0)
- F00060-06-000-04 (Private room - Deductible HK$20,000)
- F00060-07-000-04 (Private room - Deductible HK$50,000)
- F00060-08-000-04 (Private room - Deductible HK$80,000)
- F00060-01-000-03 (Semi-Private room - Deductible HK$0)
- F00060-02-000-03 (Semi-Private room - Deductible HK$20,000)
- F00060-03-000-03 (Semi-Private room - Deductible HK$50,000)
- F00060-04-000-03 (Semi-Private room - Deductible HK$80,000)
- F00060-01-000-02 (Semi-Private room - Deductible HK$0)
- F00060-02-000-02 (Semi-Private room - Deductible HK$20,000)
- F00060-03-000-02 (Semi-Private room - Deductible HK$50,000)
- F00060-04-000-02 (Semi-Private room - Deductible HK$80,000)
- F00060-01-000-01 (Semi-Private room - Deductible HK$0)
- F00060-02-000-01 (Semi-Private room - Deductible HK$20,000)
- F00060-03-000-01 (Semi-Private room - Deductible HK$50,000)
- F00060-04-000-01 (Semi-Private room - Deductible HK$80,000)
- F00060-05-000-03 (Private room - Deductible HK$0)
- F00060-06-000-03 (Private room - Deductible HK$20,000)
- F00060-07-000-03 (Private room - Deductible HK$50,000)
- F00060-08-000-03 (Private room - Deductible HK$80,000)
- F00060-05-000-02 (Private room - Deductible HK$0)
- F00060-06-000-02 (Private room - Deductible HK$20,000)
- F00060-07-000-02 (Private room - Deductible HK$50,000)
- F00060-08-000-02 (Private room - Deductible HK$80,000)
- F00060-05-000-01 (Private room - Deductible HK$0)
- F00060-06-000-01 (Private room - Deductible HK$20,000)
- F00060-07-000-01 (Private room - Deductible HK$50,000)
- F00060-08-000-01 (Private room - Deductible HK$80,000)
VHIS provider registration no. 00023 · Registration effective date: 21 March 2019
Limited-time Top up at only HK$140/month
Enjoy Annual Health Check-up Package and Optional Items
(Valued up to HK$4,220)
A. Core Health Check-up (Valued up to HK$2,720)
#Items only applicable to persons aged 18 or above
Items
Detailed Medical History
General Health Assessment
- Blood Pressure, Height, Weight,
- Body Mass Index and Waist Circumference
Eye Examinations
- Visual Acuity
- Color Vision
Cardiac Examinations#
- Electrocardiogram (ECG)
Blood Analysis#
- Complete Blood Count
Renal Function#
- Urea
- Creatinine
Liver Function#
- S.G.O.T. (AST)
- S.G.P.T. (ALT)
- Alkaline Phosphatase
Diabetes Screening#
- Glucose, Fasting
Lipid Profile#
- Total Cholesterol
- HDL Cholesterol
- LDL Cholesterol
- Triglycerides
Urine Routine Examination#
- Urine Routine
Stool Test#
- Occult Blood
- Stool Routine (Ova and Cysts) (Aged under 18)
Tumour Markers#
- Prostatic Specific Antigen (PSA) (Male)
- CA15.3 (Female)
Medical Consultation # and Report Analysis (For abnormal lab result only)
B. Optional Healthcare / Medical Services (Valued at HK$1,500)
Entitled to 1,500 BowtiePoint (valued at HK$1,500) each year for redeeming designated optional health check items based on doctor's recommendations on top of the core health check-up.
#Items only applicable to persons aged 18 or above
| Items |  =Bowtie Points required |
|---|---|
| Optional Health Check Items* must be used in conjunction with the Core Health Check-up. | |
Liver Function (Extended Profile)#
| 1,500 |
Thyroid Function#
| 500 |
Electrolytes 1#
| 300 |
Electrolytes 2#
| 500 |
Tumour Markers Panel#
| 1,500 |
Other Tumour Markers
| 600 |
| Liquid Based Pap Test (Doctor fee included)# | 500 |
Diabetes Screening#
| 300 |
| The following Optional Health Check Items can be used separately from a Health Screening Package. | |
GP Consultation — no age limitation
| 500 |
Professional Nutrition Consultation (2 sessions)
| 900 |
Vision Care
| 300 |
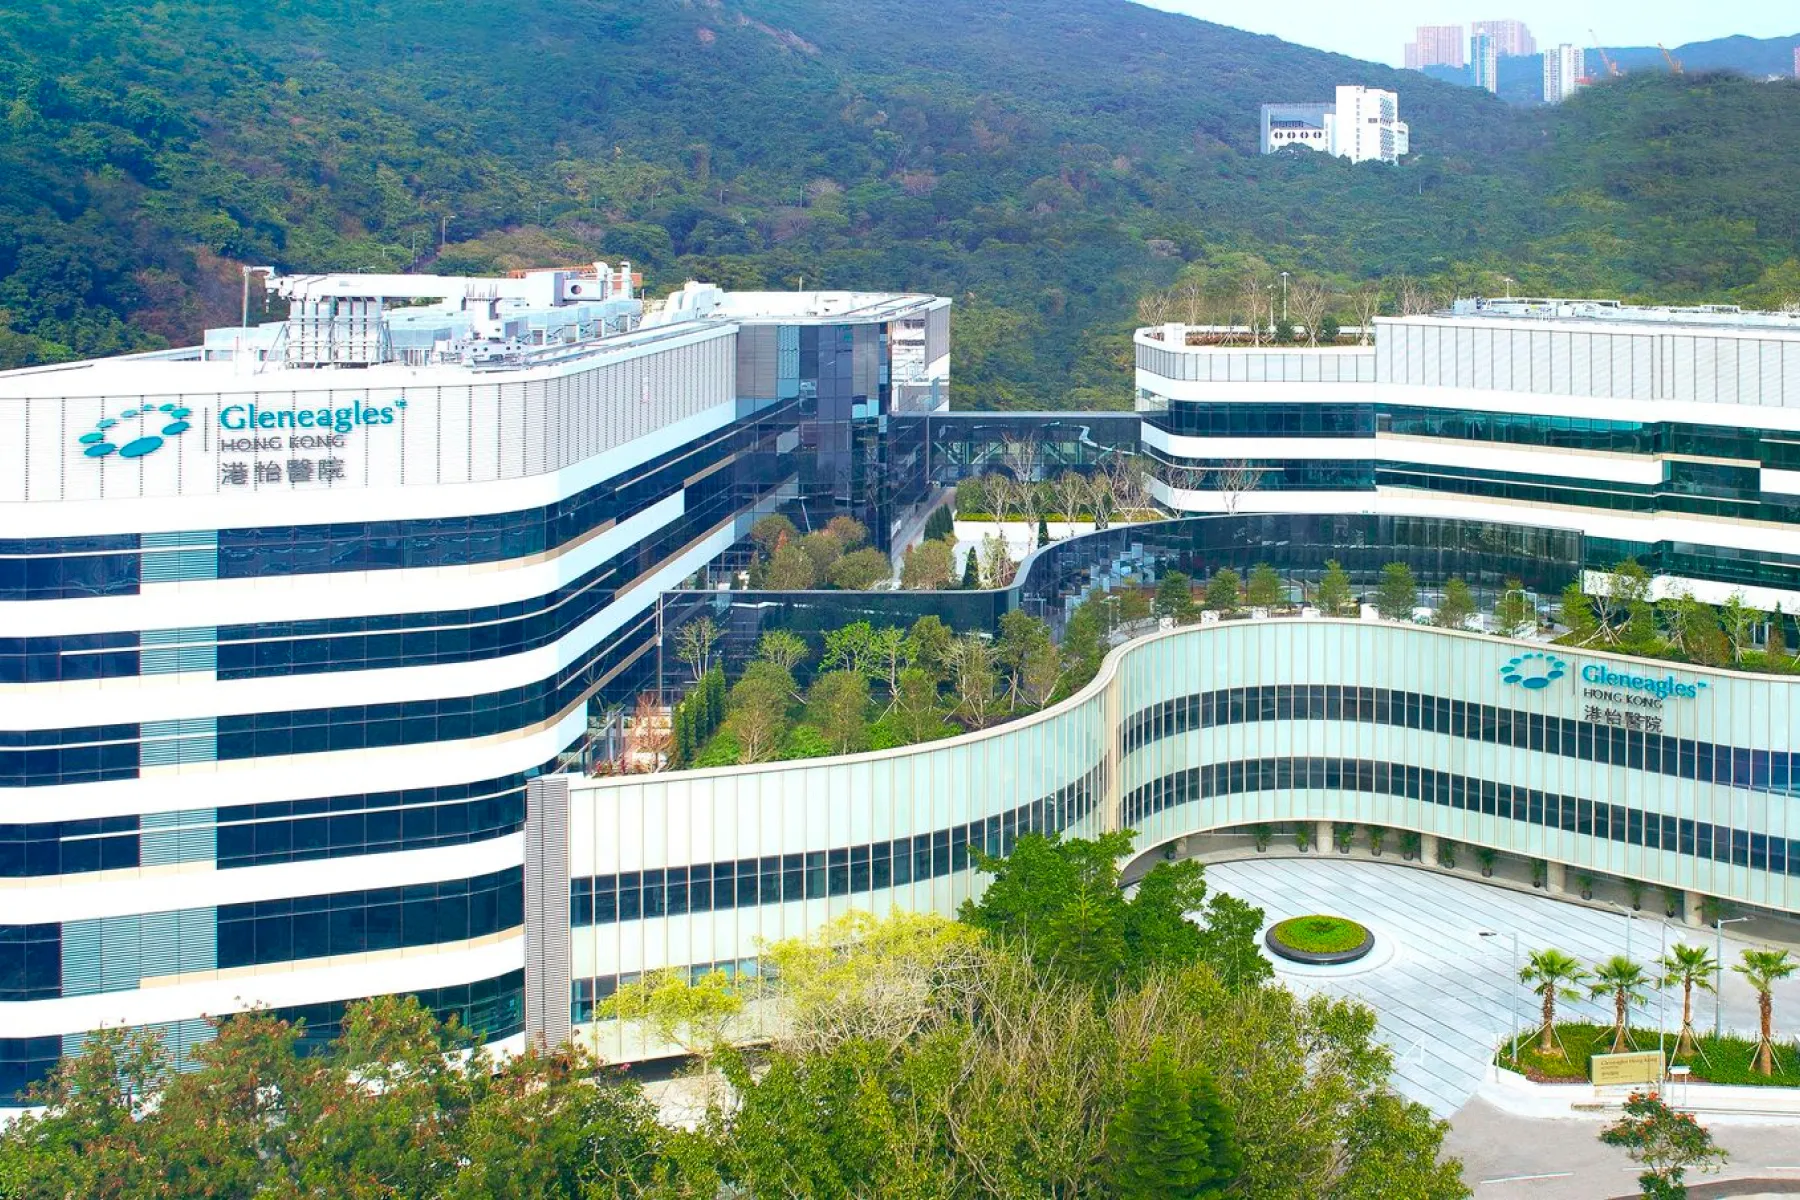
Get 1) an HK$500 Cash Benefit2 and 2) Full Cover3 (applicable to Flexi Plan customers only) for the [249] designated “All-inclusive Fixed Price Medical Packages” and “Histotripsy treatment - Liver cancer treatment package”* of GHK. The designated “All-inclusive Fixed Price Medical Packages” cover [11] specialties including Endoscopy, General Surgery, Cardiology / Cardiothoracic Procedures, Gynecology, Ophthalmology, Orthopedics, Interventional Radiology Procedures, etc. Each package includes the doctors’ fees, room charges and all other procedure-related standard items and drugs. The costs related to complications are also covered (including intensive care and re-operation charges).
💡Bowtie Pink already fully cover the costs of designated medical packages without utilizing the Wellness Package's benefits.
Remark^
1 BowtiePoint Program is not a cash reward plan. Under the Bowtie & GHK Wellness Package, BowtiePoint Program is only applicable for redemption of the “Optional Health Check Items" under the said package and it cannot be converted into cash, transferred, or accumulated for the next policy year.
2 Cash Benefit applies to the use of Designated Medical Packages and is not subject to the annual or lifetime benefit limit (if applicable) of the Bowtie VHIS Flexi or Bowtie Pink VHIS.
Cashless settlement for all designated medical packages can be processed without needing you to submit any pre-approval application. By presenting the page after logging into the Bowtie online platform that indicates your rider during a pre- surgery medical consultation, the hospital will directly submit a pre-approval application in respect of the designated medical package(s) to Bowtie on your behalf. You do not need to handle any application paperwork yourself. Upon approval of the application, you can enjoy the convenience of being discharged without having to settle the bill.
Remark GHK will submit to Bowtie on your behalf the pre-approval application in respect of the Designated Medical Packages(s) for the intended surgery(ies)/ procedure(s) for the cashless settlement service, which the cashless settlement service is subject to Bowtie's approval. For the service terms and conditions, please refer to the relevant application form.

A. Core Health Check-up (Valued up to HK$1,910)
#Items only applicable to persons aged 18 or above
Items
Physical Examination
- Blood Pressure, Height, Body Weight, Body Mass Index (BMI), Waistline
Medical Consultation and Examination by a Family Physician
Urinalysis
- Urine Routine
Coronary Artery Disease Risk Assessment
- Lipid Profile
- Total Cholesterol
- High-density Lipoprotein & Low-density Lipoprotein Cholesterol
- Non-high-density Lipoprotein Cholesterol
- Triglycerides
- Total Cholesterol / HDL ratio
Diabetes Assessment
- Fasting Blood Sugar
Liver Function Test
- Aspartate Aminotransferase (AST/SGOT)
- Gamma-glutamyl Transferase (GGT)
Renal Function Test
- Creatinine
Gout Screening
- Uric Acid
Report Explanation by Family Physician
B. Optional Healthcare / Medical Services (Valued at HK$1,500)
Entitled to 1,500 BowtiePoint (valued at HK$1,500) each year for redeeming designated optional health check items based on doctor's recommendations on top of the core health check-up. Optional Health Check Items* must be used in conjunction with the Core Health Check-up.
#Items only applicable to persons aged 18 or above
| Items | =Bowtie Points required |
|---|---|
| C-Urea Breath Test | 800 |
| Hep A Antibody (IGG) + HBSAG + HBSAB | 700 |
| Rest ECG | 600 |
| Cancer Antigen-125 (For Ovarian Cancer) | 700 |
| Prostate Specific Antigen, PSA (For Prostate Cancer) | 600 |
| Pap Smear | 600 |
| Carcinoembryonic Antigen, CEA (For Lung Cancer, Gastric Cancer, Colorectal Cancer, Ovarian Cancer, Breast Cancer, etc) | 700 |
| Vitamin D (Bone Function Test) | 700 |
| Thyroid-stimulating Hormone, TSH (For Thyroid Function) | 500 |
| Glycated Hemoglobin, HbA1C (For Diabetes) | 400 |
| AFP - alpha fetoprotein (Liver cancer) | 500 |
| Chest X Ray | 300 |
| Chlorides (Renal Function Test) | 200 |
| Sodium (Renal Function Test) | 200 |
| Potassium (Renal Function Test) | 200 |
| Fecal Occult Blood Test, FOBT (For Colorectal Cancer) | 200 |
| Bone Density Test (DEXA) - Spine & Hips (Bone Function Test) | 1,000 |
| EBV DNA (For Nasopharyngeal Carcinoma) | 800 |
| Pap Smear + HR-HPV DNA | 1,300 |
| Stool Routine | 200 |
| Breast Ultrasound | 1,500 |
| 2D Mammogram | 1,500 |
Get 1) an additional HK$500 Cash Benefit1 and 2) Full Cover2 (applicable to Flexi Plan customers only) for the designated [139] day procedure and [228] inpatient operation/procedure packages named “CUMC Medical Packages” (CMP). The designated “CUMC Medical Packages” cover [7] specialties, including General Surgery, Gynecology, Ophthalmology, Orthopedics, and endoscopy procedures. Each package includes all doctors’ fees and all hospital charges for procedure-related standard items and drugs, which also cover expenses over complications and intensive care arising from the operation/procedure.
💡Bowtie Pink already fully cover the costs of designated medical packages without utilizing the Wellness Package's benefits.
Remark
1 BowtiePoint Program is not a cash reward plan. Under the Bowtie & CUHK Medical Centre (CUHKMC) Wellness Package, BowtiePoint Program is only applicable for redemption of the “Optional Health Check Items" under the said package and it cannot be converted into cash, transferred, or accumulated for the next policy year.
2 Cash Benefit applies to the use of Designated Medical Packages and is not subject to the annual or lifetime benefit limit (if applicable) of the Bowtie VHIS Flexi or Bowtie Pink VHIS.
Cashless settlement for all designated surgery/procedure packages can be processed without needing you to submit any pre-approval application. By presenting your Bowtie Digital Medical Card that indicates your rider during a pre-surgery medical consultation at CUHK Medical Centre, the hospital will directly submit a pre-approval application in respect of the CUMC Medical Package(s) designated to Bowtie on your behalf. You do not need to handle any application paperwork yourself. Upon approval of the application, you can enjoy the convenience of being discharged without having to settle the bill.
Remark CUHK Medical Centre will submit to Bowtie on your behalf the pre-approval application in respect of the Designated Medical Packages(s) for the intended surgery(ies)/ procedure(s) for the cashless settlement service, which the cashless settlement service is subject to Bowtie's approval. For the service terms and conditions, please refer to the relevant application form.
FAQ
If I already have Bowtie VHIS, do i need Bowtie Touch Wood Protector?
It depends on your needs. All Bowtie VHIS can cover eligible medical expenses for hospitalization or surgery due to accidental injuries. The Flexi Plan and Bowtie Pink even have Accident emergency outpatient treatments that cover treatment costs at hospital outpatient departments or emergency rooms within 24 hours of the relevant accident. While Bowtie's medical insurance plan covers hospitalization and surgery costs from accidents, it also provides coverage for outpatient treatments, physiotherapy, chiropractic, and tui na massage treatments arising from accidental injuries.
Plan Comparison
| VHIS - Standard | VHIS - Flexi | Bowtie Pink | Touch Wood Protector | |
| Coverage status / Illness | Any accident or illness* | Any accident or illness* | Any accident or illness* | Any accident* |
| Basic Coverage Limit | HK$420,000/ /year, with no lifetime limit. | Regular Plan: $600,000 /year, with no lifetime limit. Plus Plan: $1,000,000 /year, with no lifetime limit. | Ward Plan: $8 million per year; $40 million per lifetime Semi-private Plan: $10 million per year; $50 million per lifetime Private Plan: $20 million per year; $80 million per lifetime | HK$420,000/ /year, with no lifetime limit. |
| Accident Outpatient | ✅ Treatment at hospital outpatient departments or emergency rooms within 24 hours of the relevant accident | ✅ Treatment at hospital outpatient departments or emergency rooms within 24 hours of the relevant accident | ✅ | |
| Physiotherapy, Chiropractic, and Tui Na Massage Treatments | ✅ | |||
| Hospitalization / Surgery Treatments | ✅ | ✅ | ✅ | ✅ |
| Territorial Scope of Cover | Worldwide except Psychiatric Treatment | Worldwide except Psychiatric Treatment, Rehabilitation Therapy, and Medical Negligence Coverage | Worldwide except the US, hospitals that are out of the List of Designated Hospitals in Mainland China and Psychiatric Treatment | Worldwide except Psychiatric Treatment |
For benefit details, please refer to the product website and policy Terms and Conditions.
*Except General Exclusion
Do BowtiePink customers still need to pay the deductible when using Designated Medical Packages after purchasing the Wellness Package as top up?
Yes. BowtiePink customers will still need to pay the relevant deductible even after purchasing the Wellness Package. Please note that since BowtiePink is already designed to fully reimburse the costs of Designated Medical Packages, customers who add the wellness package will receive an additional HK$500 cash benefit when using a Designated Medical Package.
The cash benefit under the wellness package is calculated based on the number of Designated Medical Packages used, with no limit on the number of claims. You will receive HK$500 cash benefit for each use of a Designated Medical Package. This benefit is not constrained by the annual or lifetime benefit limits of your BowtiePink policy.
For product terms and conditions, please refer to the relevant product page.
What are the differences between “Deductibles” and “Co-insurance”?
Both are medical costs that the insured must pay when filing claims from the insurance company. Their main difference lies in the calculation methods:
"Co-insurance" - Calculated based on individual protection items and percentages, shared between the insured and the insurance company.
Assume the insured must bear 20% co-insurance for a claim item, with medical costs of HK$120,000:
Compensation provided by the insurance company = HK$120,000 X 80% = HK$96,000
Costs paid by the insured = HK$120,000 X 20% = HK$24,000
"Deductible" - Calculated per policy year, the insured must bear a certain amount before the insurance company compensates the remaining medical expenses according to the plan’s coverage limit.
Assuming the insured has opt for BowtiePink with a HK$20,000 deductible, while the total hospital medical expenses are HK$70,000, Bowtie will compensate would be [Total Medical Expenses – Deductible], which is HK$70,000 – HK$20,000 = HK$50,000.
Bowtie Pink only offers deductible options (choices of HK$80,000, HK$50,000, HK$20,000, or HK$0) with no co-insurance. Whereas Bowtie VHIS Standard and Flexi have co-insurance but no deductible:
Bowtie VHIS Standard
- Prescribed diagnostic imaging tests including CT, MRI, and PET scans: 30% co-insurance^
Bowtie VHIS Flexi
- Prescribed diagnostic imaging tests including CT, MRI, and PET scans: 30% co-insurance^
- Supplementary Major Medical (SMM): 20% co-insurance*
^The reimbursement is subject to the "Benefit Limit" of the Bowtie VHIS Standard Plan or Flexi Plan.
*The reimbursement is Subject to the maximum coverage limit of Bowtie VHIS Flexi Plan's "Supplementary Major Medical" coverage.
What are the differences between Bowtie VHIS and other insurance products offered by Bowtie?
Comparison of Insurance Plans:
| VHIS | Cancer Fighter | Touch Wood Protector | Critical Illness | Term Life | |
|---|---|---|---|---|---|
| Product Nature | Not limited to any accident or disease, cover the eligible medical expenses required for hospitalization or surgery due to medical needs. | Cover the eligible medical expenses for all levels of malignant cancer and carcinoma in situ¹ | Cover the actual expenses for medically necessary treatments due to accidental injuries within 12 months after the accident. | Receive compensation to help cover living expenses or medical costs once you are diagnosed with a specified critical illness (including cancer, stroke, and heart disease) | Death Benefit |
| Modes of Settlement | Reimbursement | Reimbursement | Reimbursement | One lump sum payment | One lump sum payment |
| Maximum Benefit Limits / Sum insured | - Standard Plan : HK$420K / Year;No lifetime limits - Flexi Plan: Up to HK$1M / Year; No lifetime limits - Bowtie Pink: Up to $20M / Year; $80M /Lifetime | - Cancer Fighter 100: HK$1M /Lifetime - Cancer Fighter 200: HK$2M /Lifetime - Cancer Fighter 300: HK$3M /Lifetime | HK$420K / year | HK$4M (15 days - 45 year old) HK$2M (46 - 60 year old) HK$1M (61 - 65 year old) | HK$20M (Existing customer²) HK$8M (18 - 45 year old) HK$4M (46 - 55 year old) HK$3.5M(56 - 60 year old) HK$1M (61 - 65 year old) |
| Maximum Renewable Age | Guaranteed renewal to age 100 or for life* | Guaranteed lifetime renewal | Renewal to age 60 | Guaranteed renewal to age 85 | Guaranteed renewal to age 100 |
| Plan Option | - Standard Plan - Flexi Plan - Bowtie Pink | - Cancer Fighter 100 - Cancer Fighter 200 - Cancer Fighter 300 | - Touch Wood Protector | - Term CI - Term CI Multiple Cover - Term CI Early Stage and Multiple Cover | - Term Life |
¹ Bowtie Cancer Fighter covers all grades of malignant cancer and carcinoma in situ, excluding precancerous lesions, CIN I or CIN II cervical anomalies, or all cancers coexisting with HIV infection.cinoma in situ, excluding precancerous lesions, CIN I or CIN II cervical anomalies, or all cancers coexisting with HIV infection.
² Existing customers can increase their coverage limit up to a maximum of HK$20,000,000 after undergoing underwriting and a medical examination. Click here to learn more.
*This Applies only to the Flexible Plan and Bowtie Pink.
The above information is for reference only. For detailed terms and conditions above is for reference only. For detailed terms and conditions, key risks and policy exclusions of the product, please refer to the policy.
What is VHIS / What are the differences with Traditional Medical Insurance in the Market?
Voluntary Health Insurance Scheme (VHIS), regulated by the Health Bureau, is a personal medical insurance that reimburses eligible medical expenses related to hospitalization and day surgeries. All VHIS must meet several standardized product features including policy terms, minimum coverage, and premium transparency. Although insurers can have different coverages and designs for their Flexi Plans (Chinese only), all terms and coverages cannot be set below the standards of the VHIS Standard (Chinese only).
Comparison of VHIS and General Medical Insurance:
| VHIS | General Medical Insurance | |
| Lifetime Coverage Limit | ❌¹ | ✔ |
| Tax Benefits | ✔ | ❌ |
| Age of Insurability | 15 days - 80 years | 15 days - 70 years |
| Guaranteed Renewal Age | Guaranteed lifetime renewal, VHIS Standard guaranteed renewal until age 100 | Determined by the insurer |
| Waiting Period | ❌² | ✔ |
| Coverage for Pre-existing Conditions Unknown at the time of insuring | ✔³ | ❌ |
| Hospital and Surgical Coverage | ✔ | Covers treatments during hospital stays, may not cover non-hospital treatments |
| Psychiatric Inpatient Treatment | ✔ | |
| Day Surgery Coverage | ✔ | ❌ |
| Coverage for Congenital Diseases | ✔ (Coverage starts from age 8 for diagnosed congenital conditions) | |
| Outpatient Diagnostic Procedures like CT, MRI, PET | ✔ | ❌ |
Bowtie currently offers three VHIS plans: Standard, Flexi, and BowtiePink, each with varying coverage amounts, ward classes, and deductibles. You can view detailed plan comparisons here.
¹ VHIS Standard Plan does not have a lifetime coverage limit; individual Flexi Plans may have a lifetime coverage limit.
² VHIS Standard Plan has an exclusion period for "Unknown Pre-existing Conditions."
³ VHIS Standard Plan has a waiting period for "Unknown Pre-existing Conditions." The first policy year is a waiting period, partial coverage starts in the second year (25% in the second year, 50% in the third year), and full reimbursement (100%) begins in the fourth policy year.
If I currently do not have any medical insurance (Group / Individual Plan), how should I decide on the deductible for Bowtie Pink?
You can choose the most appropriate deductible level for the BowtiePink VHIS based on your affordability for both the deductible and premium.
Bowtie Pink offers four deductible options: HK$80,000, HK$50,000, HK$20,000, and HK$0. Higher deductible plans have lower premiums, and vice versa.
For instance, choosing the Bowtie Pink with a $20,000 deductible, of which the deductible is calculated per policy year, you bear the first HK$20,000 of eligible medical expenses each policy year, after which Bowtie compensates for the remaining eligible medical expenses.
If you have a limited budget, you might also consider a plan without a deductible, such as the Bowtie VHIS Flexi Plan or Standard Plan.
You can also use Bowtie’s personalized recommendation tool or contact us via WhatsApp at 6016 5980 for more specific product advice!
What are the differences between the 3 Bowtie VHIS Plan?
Bowtie currently offers 3 VHIS Plans, including Standard Plan, Flexi Plan, and BowtiePink, each with different coverage limits, room grades, and deductible options.
You can choose primarily based on whether you already have health insurance:
- If you do not have health insurance - VHIS Standard or VHIS Flexi
- If you already have health insurance - BowtiePink
| VHIS Standard | VHIS Flexi | Bowtie Pink | |
|---|---|---|---|
| Features | Suitable for those with a limited premium budget
| Suitable for long-term primary medical coverage
| Suitable for those looking to enhance existing health insurance coverage
|
| Basic coverage limit | HK$420,000/ /year, with no lifetime limit. |
|
|
Click here to view a detailed comparison of the plans. If needed, you can also seek for product advice via WhatsApp at 6016 5980!
What is co-insurance and which coverage items have co-insurance?
Co-insurance means that the insured person shares a portion of the costs for certain covered services on a percentage basis.
"Co-insurance" - Calculated based on individual protection items and percentages, shared between the insured and the insurance company.
Assume the insured must bear 20% co-insurance for a claim item, with medical costs of $120,000:
Compensation provided by the insurance company = $120,000 X 80% = $96,000
Costs paid by the insured = $120,000 X 20% = $24,000
Bowtie VHIS includes co-insurance for the following plans:
Bowtie VHIS Standard
- Prescribed diagnostic imaging tests including CT, MRI, and PET scans: 30% co-insurance
Bowtie VHIS Flexi
- Prescribed diagnostic imaging tests including CT, MRI, and PET scans: 30% co-insurance
Supplementary Major Medical (SMM): 20% co-insurance
Bowtie Pink
- Does not have co-insurance items
Is there any waiting period for VHIS?
Generally, there is no waiting period for illnesses that arise after you enroll in Bowtie VHIS Plan.
Bowtie VHIS only has a waiting period for "pre-existing conditions unknown to you at the time of enrolment." These are conditions that you already had before enrolling, but were unaware of because there were no obvious symptoms, and you did not seek medical advice or treatment.
In simple terms, if you were unaware that you had a certain condition when you enrolled, but are later diagnosed and need treatment for it after enrolling, the eligible expenses will be subject to the following waiting periods and reimbursement ratios.
Flexi Plan and Bowtie Pink
| Waiting Period (from the effective date of the policy) | Reimbursement ratio |
| The first 90 days | 0% |
| On and after the 91st day | 100% of the eligible medical expenses within the benefit limit |
Standard Plan
| Waiting Period (by Policy Year) | Reimbursement ratio |
| 1st policy year | 0% |
| 2nd policy year | 25% of the eligible medical expenses within benefit limit |
| 3rd policy year | 50% of the eligible medical expenses within benefit limit |
| 4th policy year onwards | 100% of the eligible medical expenses within benefit limit. |
What is a deductible? Is it calculated per illness/injury or per policy year?
"Deductible" is the amount the policyholder must pay out of pocket within the policy year when making a claim with Bowtie. The remaining medical expenses are then compensated by Bowtie up to the coverage limit of the plan.
If the insured person has a Bowtie Pink plan with a $20,000 deductible and the total medical expenses are $70,000, we will cover $50,000
Total medical expenses – Deductible = Coverage
$70,000 – $20,000 = $50,000
The Bowtie VHIS Standard and Flexible plans do not come with a deductible, whereas Bowtie Pink’s deductible is calculated annually. For instance, if the policy starts on December 1, 2021, from December 1, 2021, to November 30, 2022 (the first policy year), you must first bear HK$20,000 of medical expenses (including amounts claimed from your company’s group medical insurance), and after which Bowtie compensates for the remaining eligible medical expenses.
Additionally, we recommend that even if your medical expenses are lower than the deductible for your Bowtie Pink plan, you should still submit all hospitalization/surgery-related medical receipts and proof of reimbursement from other insurance companies (if applicable) to Bowtie. If the expenses are eligible medical expenses, they will be counted towards the deductible you have paid for that policy year with Bowtie, reducing the remaining deductible you need to pay for the same year.
Finally decide on the best deductible option for you?
Buy Bowtie Pink Now!Is there a minimum confinement duration requirement for Bowtie VHIS?
”Confinement“ shall mean an admission of the Insured Person to a Hospital that is recommended
by a Registered Medical Practitioner for Medical Service and as an Inpatient as a result of a Medically Necessary condition for a period of no less than 6 consecutive hours. The Insured Person must stay in the Hospital continuously for the entire period of Confinement. You will need to provide the daily room charge invoiced by the Hospital when submit the claims. For emergency treatments involving surgery or other medical services in a hospital, there is no minimum hospitalization time requirement.
In addition to hospitalisation treatment, Bowtie VHIS also covers Day Case Procedure such as endoscopies, without any minimum hospitalisation time requirement.
Does Bowtie VHIS include death benefits?
No, Bowtie VHIS does not include death benefit. Bowtie VHIS is an individual medical insurance that only covers eligible medical expenses for hospitalization and surgery on a reimbursement basis.
The only exception is if the insured unfortunately passes away due to medical negligence in Hong Kong, in which Bowtie VHIS Flexi and BowtiePink will then provide a "Medical Negligence Coverage" of HK$1,000,000.
If you are looking for a product that offers death benefits, do consider purchasing Bowtie Term Life.
Does the Bowtie VHIS Plan cover colonoscopy / gastroscopy expenses?
Yes. Colonoscopy / gastroscopy is classified as a minor surgery. If the insured person undergoes a colonoscopy / gastroscopy upon a doctor's recommendation, the examination is eligible for claim reimbursement, whether performed as an inpatient or day surgery procedure.
However, please note that if the colonoscopy / gastroscopy is solely for preventive treatment or preventive care—including but not limited to general health check-ups, routine tests, or screening procedures performed without any symptoms—it falls outside the coverage scope of the Bowtie VHIS Plan.
Does Bowtie VHIS reimbursement only limit to certain diseases and treatments?
No. Bowtie VHIS reimburses for any accident or disease (except General Exclusion), covering eligible medical expenses related to hospitalization and surgery, including day surgeries and diagnostic procedures like gastroscopy, CT scans, MRI, etc. Common treatment claims include circumcision, appendectomy, hospital treatment for accidents, and cataract surgery.
However, it does not cover treatments unrelated to hospitalization and surgery such as common cold, dental treatments, and outpatient treatments. Exclusions mainly include any non-medical treatments, procedures, medications, tests, or services; dental costs and oral maxillofacial surgery (except emergency treatments and surgeries due to accidents during hospitalization); and traditional Chinese medicine treatments.
Review the coverage table and general exclusion for more detailed compensation limits, covered surgical procedures, and categories. You may also use the Bowtie Claim Calculator for more examples of claims and compensation rates.
Does Bowtie VHIS cover prescribed non-surgical cancer treatments?
Yes, all the Bowtie VHIS can cover Prescribed Non-surgical Cancer Treatments including Radiotherapy, Chemotherapy, Targeted therapy, Immunotherapy, Hormonal therapy. The benefits limits for each plan is as follows:
| Standard Plan | Flexi Regular Plan | Flexi Plus Plan | All Bowtie Pink | |
| benefits limits of Prescribed Non-surgical Cancer Treatments | HK$80,000 / year | HK$80,000 / year | HK$160,000 / year | Full Cover |
What is “Day Case Procedure Cash Benefit” and how much is the coverage amount?
If an insured undergoes surgery at any out-patient surgical center or being treated as an out-patient case patient, while the surgical cost is compensated under the "Surgical Fees" coverage, s/he is eligible for “Day Case Procedure Cash Benefit”, which is calculated per surgical procedure.
Bowtie VHIS Flexi and Bowtie Pink both offer "“Day Case Procedure Cash Benefit," with coverage amounts specific to each plan. For detailed coverage amounts listed as follow:
| Flexi (Regular) | Flexi (Plus) | Bowtie Pink |
|---|---|---|
| HK$800 / procedure | HK$1300 / procedure | HK$1300 / procedure |
Does Bowtie VHIS provide coverage overseas? Will the cover remain effective if I immigrate or leave Hong Kong?
Yes. The plan provides worldwide coverage. And The coverage shall remain effective whether the Insured Persons plan to reside overseas temporarily or permanently*. The policy reimbursement rate also will not be affected.
Scope of Coverage for Each VHIS Plan:
| VHIS Standard | VHIS Flexi | Bowtie Pink | |
| Coverage Area | Global (excluding psychiatric treatment) | Global (excluding psychiatric treatment, rehabilitation, and medical negligence coverage) | Global (excluding the US and non-designated hospitals in China); Psychiatric treatment limited to Hong Kong only |
At the time of insurance purchase, both the policyholder and the insured must reside in Hong Kong. The policy remains effective even if the insured relocates overseas temporarily or long-term (except in sanctioned or war-affected areas).
However, due to potentially higher risks in the country of relocation, additional premiums may be charged for those regions. Policyholders can choose not to renew if they disagree with the proposed additional premium adjustments. Short stays in other countries, or travel, work, or study abroad do not incur extra premiums.
Please notify Bowtie of any changes in address. For further inquiries, call customer service at 3008 8123.
*except for places of residence affected by sanctions or war
Can individuals who have had or currently have COVID-19 apply for Bowtie VHIS?
Bowtie currently accepts applications from individuals who have recovered from COVID-19 for more than one month. Applications from those currently suffering from COVID-19 or those who test positive are not accepted at this time.
For individuals who currently still being tested positive for COVID-19, we welcome them to submit their application one month after recovery.
Reach out to Bowtie CS at 3008 8123 for more details.
Is health assessments required for underwriting before purchasing Bowtie VHIS?
Not required. Except for individuals over age 65 purchasing BowtiePink, you simply need to visit the Bowtie VHIS website, click "Apply Now", and complete the health declaration (underwriting questions).
We will base on your response in the health declaration in understanding any of your previously diagnosed conditions and their severity. Generally, we are able to calculate the most fair and accurate premium instantly. Most of the questions in the health declaration (95%) are multiple-choice.
The insured person whose age is between 66 and 80 must go to designated clinics to complete the following health assessments for underwriting, after applying for Bowtie Pink.
- Health questionnaire
- Resting electrocardiogram
- Urinalysis
- Blood tests include: i) liver function test, ii) kidney function test, iii) complete blood count, iv) lipid (cholesterol), v) fasting blood glucose, vi) glycosylated hemoglobin and vii) hepatitis B surface antigen
Can I hold the same Bowtie VHIS policy with my family and friends?
No. Each Bowtie VHIS Standard, Flexi, or Bowtie Pink Plan can only have one policyholder and one insured person. However, policyholders can apply for their eligible family members:
- Policyholder's spouse
- Children¹
- Siblings²
- Parents, grandparents, or spouse's siblings, parents and grandparents³
¹ Refers to children who are under 18 years old / 18 years old but under 25 years old and receiving full-time education / 18 years old or older but unable to work due to physical or mental incapacity.
² Refers to siblings who are under 18 years old / 18 years old but under 25 years old and receiving full-time education / 18 years old or older but unable to work due to physical or mental incapacity.
³ Refers to individuals under 55 years old who are eligible to apply for benefits under the government's disability allowance scheme / 55 years old or older.
If I already have medical insurance (Group/ Individual Medical Plan), how should I choose the Bowtie VHIS that is the most appropriate?
You can consider Bowtie Pink VHIS with a deductible to supplement your existing health insurance (commonly known as "Top-Up" insurance), which can enhance protection while also helps saving on premiums.
Based on the coverage level of your company's group medical insurance, you can decide on an appropriate deductible. When you need to file a claim, you can first claim it from your company's group medical insurance, and the remaining eligible medical expenses, after deducting the deductible, can be covered by Bowtie Pink.
For example, if you opt for the Bowtie Pink VHIS plan with a HK$20,000 deductible, of which the deductible is calculated per policy year, meaning you need to bear the first HK$20,000 of eligible medical expenses each policy year (including expenses claimed from company health insurance), after which Bowtie will cover for the remaining eligible medical expenses.
If needed, you can also seek product advice via WhatsApp at 6016 5980!
Bowtie offers various products with different levels of coverage. You can consider and choose the most appropriate insurance product based on your personal needs and financial capacity.
Is there a maximum/minimum age limit for enrolling in the Bowtie VHIS?
Bowtie VHIS accepts enrollments for Hong Kong residents aged between 15 days and 80 years. Apart form individuals aged 66 and above applying for the BowtiePink, health assessment is not required for underwriting prior to purchasing a policy.
Once successfully insured, Bowtie VHIS Standard guarantees renewal up to the age of 100, while Bowtie VHIS Flexi and BowtiePink offer lifetime renewals in addition.
Is an insured person allowed to hold multiple Bowtie VHIS policies?
Yes, an insured person can hold multiple Bowtie VHIS policies. Currently, each insured person can hold either:
- Two Bowtie VHIS Standard, or
- One Bowtie VHIS Standard + One Bowtie Flexi
- One Bowtie VHIS Standard / Flexi + one Bowtie Pink (with a deductible of $20,000 / $50,000 / $80,000)
However, if an insured person currently holds a Bowtie Pink VHIS with $0 deductible, one cannot purchase for any other Bowtie VHIS policies.
What is BowtieCash and what is it for?
BowtieCash can be used to pay any eligible medical expenses that exceed the compensation amount of the Bowtie VHIS, with the exception for the Bowtie Pink deductibles and to redeem comprehensive health services such as full-body health check-ups.
How to earn BowtieCash*?
Bowtie VHIS customers can earn BowtieCash through the "No Claims Reward Program." If the insured has no claims for six consecutive months after the policy is in effect, they can earn BowtieCash amounting to 8% of their monthly premium. The BowtieCash is valid for 7 years.
For more details, please visit this website.
*Bowtie VHIS No-Claim Rewards is subject to terms and conditions.
How to Use Global Emergency Assistance Services?
All insured persons of Bowtie VHIS customers, including Bowtie VHIS Standard, Bowtie VHIS Flexi - Regular / Plus, and Bowtie Pink(Ward/ Semi-Private/ Private) will automatically be entitled to the worldwide emergency assistance service provided by our business partner - Europ Assistance Hong Kong Limited (EAHK), to provide assistance when the insured person is on business or traveling overseas.
The insured should contact the EAHK the 24-hour worldwide emergency and medical helpline at +852 2863 5767 and provide the following information for assistance, the insured is also welcomed to have their friends or family to contact EAHK on his/her behalf as proxy. If the insured person fails to contact EAHK before hospitalization or treatment, the insured person or his/her representative shall contact EAHK within 3 days of the occurrence of such emergency. Otherwise, assistance may not be obtained.
Required information:
- Name of insured
- ID or passport number of the insured
- Policy number
- The name, address and telephone number of the hospital or other medical facility where the insured life has been attended, and the name, address and phone number of the attending physician and, if necessary, the family doctor of the insured. (Applicable to the repatriation services)
The worldwide emergency assistance service includes:
- Medical Attention, Telephone Medical Advice, Evaluation and Referral Appointment
- Medical Evacuation
- Repatriation after Treatment
- Repatriation of Mortal Remains/Ashe
- Medical Monitoring
- Travel Information
- Hotel Room Accommodations for Convalescence
- Compassionate Visit
- Return of Unattended Dependent Child(ren) to Country of Residence
- Dispatch Essential Medication/ Medical Equipment
- Dispatch Physician from Hong Kong
- Guarantee of Hospital Admission Deposit and Medical Expenses Incurred during Hospitalization
- Medpass - Hospital Admission Guarantee in China Network Hospital
Note: “Worldwide Emergency Assistance Service” does not form part of the Bowtie VHIS Plans and is provided by third-party service provider. We reserve the right to change the the content of “Worldwide Emergency Assistance Service” and will not be liable for any services provided by third-party service provider. No additional premiums are charged for this service.
How to effectively utilize Bowtie Pink's deductible with existing medical insurance for medical claims?
You can first claim from your group medical insurance or another insurance plan without a deductible. After that, you can claim from Bowtie Pink. The payout from your company's insurance can be used to offset the deductible for Bowtie Pink, effectively reducing the amount you need to pay out-of-pocket.
Example:
Suppose you choose the BowtiePink plan with a HK$20,000 deductible and you undergo surgery due to illness with a total eligible hospitalization costs: HK$40,000
Company’s group medical insurance coverage limit: HK$30,000
First claim from the group medical insurance to receive HK$30,000 compensation, which offsets the deductible under BowtiePink.
The remaining medical expenses of HK$10,000 (i.e., HK$40,000 - HK$30,000) are fully reimbursed by BowtiePink, leaving you with no out-of-pocket hospital expenses.
The above advice is for reference only and does not guarantee no out-of-pocket expenses. You should consider your actual situation and coverage.
If the medical expenses do not exceed the deductible amount for Bowtie Pink, do I still need to file a claim with Bowtie?
Yes, we recommend that even if your medical expenses are lower than the deductible for your Bowtie Pink plan, you should still submit all hospitalization/surgery-related medical receipts and proof of reimbursement from other insurance companies (if applicable) to Bowtie. If the expenses are eligible medical expenses, they will be counted towards the deductible you have paid for that policy year with Bowtie, reducing the remaining deductible you need to pay for the same year.
Can I change the deductible option for my Bowtie Pink plan?
Yes, You can log in to the Bowtie online platform to apply to change the deductible option at least 30 days before the next annual renewal date. The new plan will take effect on the next annual renewal date of the original plan, and the premium will start to be charged from that day, while the original plan will be terminated on the same day. The new plan will retain the policy number of the original plan, and valid policy benefits, BowtieCash and past claim records will also be retained.
Application method: Log in to the online member portal → Select the relevant policy → Click Modify Policy
If the application involves an increase in coverage, the application will need to be re-underwritten, and the waiting period for "unknown pre-existing conditions" under the new plan will be recalculated to ensure overall customer fairness. The coverage results may be different from the original plan, but you do not need to submit your personal information and conduct identity verification again. The arrangements for different applications are as follows:
| Original Plan | New Plan | Re-underwriting and recalculation of waiting period for "unknown pre-existing conditions" |
| Bowtie Pink ($20K / $50K / $80K Deductible) | Higher ward class with the same deductible | ✅ |
| Higher ward class with a lower deductible* | ✅ | |
| Higher ward class with a high deductible | ✅ | |
| Same ward class with a lower deductible* | ✅ | |
| Lower ward class with a lower deductible* | ✅ | |
| lower ward class with the same deductible | ||
| lower ward class with a higher deductible | ||
| same ward class with a higher deductible | ||
| Bowtie Pink ($0 Deductible) | Higher ward class with the same deductible | ✅ |
| Higher ward class with a higher deductible | ✅ | |
| lower ward class with the same deductible | ||
| lower ward class with a higher deductible | ||
| same ward class with a higher deductible |
* If a Bowtie Pink VHIS insured person meets the following two requirements, the policyholder may exercise a one-time right to lower or cancel the deductible within a specified period without undergoing re-underwriting and without providing proof of insurability for the insured person:
1. The relevant Bowtie Pink VHIS plan has been continuously effective for 2 years or more;
2. The insured person is 55, 60, 65, 70, 75, or 80 years old.
The policyholder may exercise this right on the day the insured person reaches the above age or at least 30 days before the next policy renewal date following that age, lowering the deductible to the options available at that time. Please note that this right can only be exercised once in a lifetime per insured person.
In any case, the premium after changing the deductible will be adjusted according to the then-applicable standard premium schedule and relevant terms. For details, please refer to the policy terms and conditions Supplement No.1.
Is there an upper age limit for renewing the VHIS plan?
Bowtie VHIS guarantees lifetime renewability at the maximum. As long as you are paying the premium on time, there is no need to worry about losing coverage in the future. The maximum renewal ages for the three Bowtie VHIS plans are as follows:
| VHIS Standard | VHIS Flexi | BowtiePink |
| 100 years | Lifetime | Lifetime |
Will my renewal premiums increase due to claims? Will I be refused coverage due to a claim?
Bowtie will not increase your VHIS premiums or terminate your policy due to your past claims in Bowtie.
In fact, VHIS guarantees renewal. Once the policy is in effect, Bowtie VHIS Standard guarantees renewal till age of 100, while the VHIS Flexi Regular/ Plus and Bowtie Pink guarantee lifetime renewal. The annual renewal premiums will only be adjusted based on age and will never be increased due to individual’s claims history or health conditions after the policy is in effect.
Not all medical insurance on the market guarantees renewal.
Want to make sure you are protected once policy is in effect?
Buy VHISTalk to a real person

 Sun, Warren | Product Specialist
Not sure which product is right for you?
We offer commission-free, 1 on 1 product consultations to genuinely help you choose the right coverage!
 Consultation booking hours:
Mon–Fri: 9:30am–6:30pm
Closed on Sat, Sun & public holidays
Product & policy service enquiries
Coverage details, existing policies, application status, underwriting questions
 Phone / WhatsApp service hours:
Mon–Fri: 9:30am–6:30pm
Sat & Sun: 2:00pm–6:00pm
(WhatsApp enquiries only)
Closed on public holidays
 Live Chat: click "Chat" at the bottom-right of the page
or email cs@bowtie.com.hk
By booking a time, you confirm you have read Bowtie's Personal Information Collection Statement and consent to the use and transfer of your personal data in accordance with it for the purpose of this enquiry.
The above information is for reference only. For detailed terms and conditions of the product, key risks, and exclusions, please refer to the policy. Bowtie Life Insurance Company Limited (Bowtie) is a limited liability company incorporated in Hong Kong. Bowtie Pink VHIS Plan is underwritten by Bowtie and intended for sale in Hong Kong only. If you see a "+" symbol, you can click on it to view more information.
Remarks
- ¹
- Based on Bowtie's market survey conducted on 17 March 2026, comparing seven high-end VHIS plans on the market that are available online and offer full reimbursement, semi-private room cover, a $0 deductible option and the same geographical coverage. Bowtie Pink had lower total premiums for non-smoking males aged 35 to 65, calculated using the average of total premiums. The premiums above have been rounded. Different medical insurance plans offer different coverage and benefit amounts. Please refer to the relevant policies and their terms and conditions for details. These premium calculations are for reference only. Your actual premium is affected by time, inflation, underwriting and other factors, and the premium levy collected by the Insurance Authority must be added.
- ²
- Full reimbursement means there are no itemised benefit limits, and applies to designated benefit items only. Benefits payable are subject to the remaining deductible (if applicable), the annual benefit limit, the lifetime benefit limit and other limitations, including reasonable and customary charges, the list of designated hospitals in Mainland China and treatment received in the United States. For detailed product terms and conditions, product risks and exclusions, please refer to the relevant product website and the policy.
- ^
- Based on publicly available information, as of April 2025, the average approval rate for claims under Bowtie VHIS Standard Plan, Flexi Plan (Regular), Flexi Plan (Plus) and Bowtie Pink was 98.3%, higher than the VHIS market's annual average claims approval rate from April 2019 to the end of 2023.
- ⁺
- Bowtie follows the principle of paying all claims that should be paid. All claims remain subject to the policy terms and conditions, including coverage, reasonable and customary charges, and disclosure requirements.
- ³
- From December 2024 to November 2025, the median assessment time for Bowtie VHIS claims was 6 working days. Actual claim outcomes and processing times depend on individual circumstances, health conditions and the documents submitted.
- ⁴
- Worldwide emergency assistance services do not form part of Bowtie VHIS and are provided by a third-party service provider. We reserve the right to change these services and accept no liability for services provided by the third-party provider. No additional premium is required for these services.
- ⁵
- Bowtie Pink provides worldwide coverage, but full reimbursement does not apply in the United States or at non-designated hospitals in Mainland China. Psychiatric treatment is covered in Hong Kong only. If the insured person emigrates, we will assess the application and respond as soon as possible. Premiums may be adjusted according to the potential risks of their future place of residence. For details, please contact Bowtie Customer Service on 3008 8123.
- ⁶
- The cashless service applies to inpatient treatment only and requires prior approval from Bowtie. For the service terms and conditions, please refer to the relevant application form.
- ⁷
- BowtieGo is a wellness membership plan managed by Bowtie Life Insurance Company Limited. Its outpatient services are not an insurance product.
- ⁸
- The BowtieCash customer rewards programme is a benefit available only with Bowtie VHIS. It may only be used to pay eligible medical expenses exceeding the amount reimbursed under Bowtie VHIS and to redeem health check-ups. It is not a cash rewards programme and does not form part of Bowtie VHIS.
