Insurance
Insurance
Senior Fall Accident Claims in Hong Kong: Indoor vs Outdoor Fall Insurance and Protection Guide
Author
Bowtie Team
Updated on
2026-09-07
Senior accidental falls represent one of the most critical health and financial hazards facing ageing families in Hong Kong, frequently triggering steep emergency, surgical, and rehabilitative medical bills. Whether an elderly family member slips on slick bathroom tiles at home or loses balance on a steep outdoor pavement, having the right insurance coverage and knowing how to file a senior fall accident claim can substantially reduce out-of-pocket healthcare costs.

Senior falls in Hong Kong occur frequently in both domestic environments and public spaces, with each setting presenting distinct physical hazards that require swift medical intervention. According to data from the Department of Health, unintentional falls are the leading cause of injury-related hospitalisation among older adults aged 65 and above, accounting for the vast majority of accidental trauma episodes across the territory.
While falls can happen anywhere, the mechanisms and injury profiles differ noticeably between indoor and outdoor locations:
Common Indoor Fall Scenarios: The majority of senior falls happen right at home. Typical risk factors include smooth and wet bathroom tiles without anti-slip mats, loose rugs or telephone wires across corridors, poor nighttime lighting when navigating between the bedroom and toilet, and losing balance while getting out of bed or standing up from low sofas.
Common Outdoor Fall Hazards: Hong Kong’s dense urban layout and hilly topography create significant external dangers. Uneven pedestrian pavements, cracked kerbs, slippery steps during rainy typhoon seasons, sudden jerks on public transport, and steep escalators at high-traffic MTR stations frequently lead to sudden tumbles.
Physical Severity and Consequences: Older bones have reduced density, meaning a low-velocity impact often causes severe fractures (such as hip, femur, wrist, or vertebral compression fractures) and traumatic head injuries. According to the Elderly Health Service of the Department of Health, approximately 15.7% of community-dwelling elders experience falls annually, with nearly 10% sustaining fractures.
Financial Burden: Managing acute fall trauma incurs substantial costs. An injured parent may require ambulance transfer, emergency department attendance, emergency orthopaedic surgery, internal fixation hardware, days in a general ward, and subsequent months of physiotherapy or traditional Chinese medicine bone-setting.
Senior fall insurance reimbursements through personal accident policies cover eligible, medically necessary expenses arising directly from external slips, trips, and tumbles across indoor and outdoor settings. Unlike standard outpatient clinical benefits that carry small per-visit caps, accident medical reimbursement policies are designed to absorb unpredictable acute treatment and downstream rehabilitation costs.
Eligible fall-related claims generally encompass five core medical benefit categories:
Accident Medical Reimbursement: Policies typically reimburse actual medical and hospitalisation costs incurred within 12 months from the date of the accidental fall, up to the policy’s annual or per-incident limit.
Outpatient Emergency and Specialist Care: Immediate consultations at Hospital Authority Accident and Emergency (A&E) departments, private 24-hour outpatient clinics, registered general practitioners, and specialist orthopaedic reviews are reimbursable.
Diagnostic Investigations: When an attending doctor suspects skeletal fractures or internal cranial bleeding, prescribed diagnostic imaging—including digital X-rays, magnetic resonance imaging (MRI), and computed tomography (CT) scans—is covered under medical expense benefits.
Inpatient Hospitalisation and Day Surgery: If a fall results in an unstable bone fracture or severe joint dislocation requiring closed reduction, plaster cast immobilisation, open reduction and internal fixation (ORIF), or surgical wound debridement, associated operating theatre fees and ward accommodation are covered.
Post-Trauma Rehabilitation Therapies: Effective recovery often requires specialised post-acute care. Comprehensive plans cover treatments performed by legally registered physiotherapists, chiropractors, and registered Chinese medicine practitioners specialising in bone-setting (dit da).
A senior fall claim can be rejected by insurers if the fall was triggered by an internal medical condition rather than an external accident, or if standard contractual submission deadlines are missed. Understanding these exclusions prevents unexpected claim disputes when assisting elderly parents.
Accident Definition Constraints: Under insurance contract law, an accident is defined as an unforeseen event caused solely, directly, and independently of all other causes by external, violent, and visible means. If an external physical hazard (such as a puddle of water or an uneven pavement) did not directly induce the slip, the incident may not qualify as a pure accident.
Illness-Triggered Falls: If an elderly person collapses due to a dizzy spell (vertigo), sudden fainting (syncope), transient ischaemic attack, acute stroke, orthostatic hypotension, or cardiac arrhythmia, insurers classify the primary cause as an underlying illness. Any resulting bodily harm is excluded from personal accident compensation.
Pathological and Spontaneous Fractures: When a bone breaks simply under physiological stress or severe underlying osteoporosis without substantial external impact, it is categorised as a pathological fracture and excluded under personal accident policies.
Failure to Seek Timely Treatment: Most accident contracts require the insured person to seek professional medical attention within a stipulated timeframe—typically within 24 to 48 hours of the incident. Delaying medical consultation weakens the causal link between the fall and the injury.
Inadequate Clinical Documentation: If the consultation notes recorded by the attending emergency doctor state that the patient felt faint before dropping to the ground, rather than tripping over an obstacle, claims assessors will decline accident reimbursement on grounds of internal illness.
Filing an accident claim smoothly requires prompt medical evaluation and meticulous preservation of medical records from the moment the tumble occurs. Following this sequential checklist ensures that adult children and caregivers present complete documentary evidence to the insurer.
Obtain Immediate Medical Treatment: Take the injured senior to a registered medical practitioner or hospital emergency room immediately. Clearly explain the precise external circumstance (e.g. “tripped on a raised curb” or “slipped on wet bathroom tiles”) so that the physician writes the exact external accident cause into the official consultation notes.
Gather Original Itemised Invoices: Retain all official, breakdown receipts showing consultation fees, surgical procedures, diagnostic charges, medications, and rehabilitation costs. Ensure receipts state the patient’s full legal name and consultation date.
Secure Doctor Referral Letters: If the treating doctor recommends subsequent rehabilitation, obtain formal written referral letters for physiotherapy, chiropractic care, or imaging diagnostics prior to commencing those treatments.
Request Diagnostic Imaging Reports: Collect formal copies of X-ray, CT, or MRI radiologist reports that explicitly state the diagnosis, such as hairline fractures or ligament tears.
Submit via the Digital Claim System: Complete the insurer’s online claim submission form within the mandatory filing window (usually within 30 days of treatment). Provide a clear, chronological description specifying the accident date, exact location, and physical sequence of events.
Verify Consultation Sub-Limits: Cross-check policy limits for alternative therapies, particularly daily or annual caps for registered Chinese bone-setting and outpatient physiotherapy sessions.
Personal accident (PA) insurance plays a dedicated role in absorbing unexpected medical costs arising from sudden external physical trauma, such as slips, trips, and fractures. For families reviewing protection for ageing parents, understanding both what accident insurance excels at—and where its inherent boundaries lie—is essential before choosing a policy.
Personal accident policies are primarily designed to provide fast, straightforward reimbursement for immediate out-of-pocket medical bills caused by external accidents. Key advantages include:
Accidental Medical Expense Reimbursement: Covers immediate clinical consultations, diagnostic imaging (such as X-rays, CT, or MRI scans), wound treatment, and surgical intervention resulting directly from an external fall, subject to per-incident or annual limits.
Post-Trauma Rehabilitation Support: Standard accident policies frequently cover non-hospital outpatient recovery sessions, including legally registered physiotherapists, chiropractors, and registered Chinese medicine practitioners specialising in bone-setting (dit da).
Affordable Premiums and Simplified Underwriting: Because accident policies cover purely external physical events rather than chronic illnesses, premiums are generally modest and underwriting is straightforward, rarely requiring extensive medical health checks.
Despite its utility for sudden acute trauma, relying solely on accident insurance for elderly parents presents distinct limitations:
Strict Definition of “Accident”: Coverage applies solely to unforeseen events caused directly and independently by external, violent, and visible means. If an elderly parent falls as a result of an internal medical episode—such as a dizzy spell (vertigo), sudden fainting (syncope), transient ischaemic attack, stroke, or drop in blood pressure—insurers classify the incident as illness-induced, and resulting injuries are excluded.
Stringent Entry and Renewal Age Caps: Most personal accident policies in Hong Kong are designed around working-age individuals and enforce low age ceilings. New applications are often capped between ages 55 and 70. As fall risks escalate significantly for seniors in their late 60s, 70s, and 80s, standard PA plans often expire precisely when senior parents need coverage most.
Exclusion of Degenerative and Pathological Conditions: Fractures occurring primarily due to severe underlying osteoporosis or natural joint degeneration without substantial external impact are treated as pathological fractures and excluded.
Rehabilitation Sub-Limits: Outpatient bone-setting, physiotherapy, and chiropractic benefits are subject to daily visit caps and maximum annual visit quotas, which may not fully absorb long-term rehabilitative care after severe mobility loss.
When elderly parents exceed the age eligibility limits of personal accident plans, or when their falls stem from underlying chronic illnesses, the Voluntary Health Insurance Scheme (VHIS) serves as the primary medical safety net. Unlike accident policies that enforce narrow mechanical definitions of trauma, VHIS covers necessary hospitalisation, specialist investigations, and surgical procedures regardless of whether an admission was caused by an external trip or an internal medical episode like a dizzy spell or stroke.
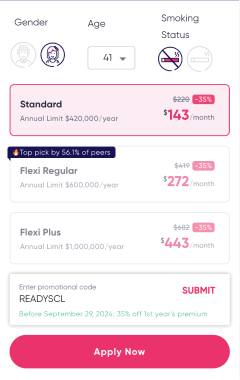
For adult children seeking comprehensive fall and hospitalisation coverage for their ageing parents, Bowtie VHIS (Standard, Flexi, and Pink) offers essential structural advantages:
Higher Entry Age: Bowtie VHIS accepts new policy applications up to age 80 (eligible from age 15 days), allowing elderly parents who are completely locked out of accident insurance to secure protection.
Guaranteed Long-Term Renewal: Bowtie VHIS Standard guarantees annual renewal up to age 100, while Bowtie VHIS Flexi and Bowtie Pink provide lifetime guaranteed renewal. Insurers cannot cancel the policy or impose targeted individual loading simply because an elderly parent has aged or lodged previous fall claims.
Full Inpatient and Surgical Coverage: If a severe fall causes a fractured neck of femur or intracranial haemorrhage, Bowtie VHIS covers inpatient ward charges, anaesthetist fees, operating theatre costs, and surgical implants. Most importantly, benefits are payable even if the fall was triggered by internal vertigo, syncope, or a mild stroke.
Emergency Accidental Outpatient Benefit: Under Bowtie VHIS Flexi and Bowtie Pink, emergency outpatient treatment received at an emergency department or clinic within 24 hours of an accident is reimbursable.
Coverage for Unknown Pre-Existing Conditions: Bowtie VHIS plans include standard statutory protection for unknown pre-existing conditions, reimbursing 0% in policy year 1, 25% in year 2, 50% in year 3, and 100% from year 4 onwards.
Salaries Tax Deductions: Adult children who act as policyholders and pay premiums for their eligible dependent parents can claim a tax deduction under Hong Kong Salaries Tax and Personal Assessment, up to an annual limit of HK$8,000 per insured person.
Pure personal accident insurance policies generally exclude falls caused directly by internal illnesses, sudden fainting, vertigo, or hypotension, because the event does not meet the contractual definition of an injury caused solely by external, violent, and accidental means. However, medical insurance such as Bowtie VHIS covers medically necessary hospitalisation, imaging, and surgical procedures regardless of whether the fall was sparked by an internal health condition or an external trip.
Yes. Bowtie Touchwood reimburses treatments administered by legally registered Chinese medicine practitioners (including bone-setting) and physiotherapists for injuries sustained in an accidental fall. For bone fractures, the plan reimburses up to HK$500 per visit (up to 6 visits per item); for non-fractures, it reimburses up to HK$250 per visit (up to 4 visits per item), subject to an aggregate maximum of 8 visits per policy year across all rehabilitation benefits.
Bowtie Touchwood accepts new applications for individuals aged between 2 and 55 years old. Existing policyholders can renew coverage annually up to the age of 60 on a non-guaranteed renewal basis. Once the insured individual reaches 60 years of age, the policy terminates.
If your parents are aged 60 or above, Bowtie VHIS plans (Standard, Flexi, or Bowtie Pink) represent an effective medical safety net. Bowtie VHIS accepts applicants up to age 80 and guarantees renewal up to age 100 (Standard) or for life (Flexi and Pink). It covers major inpatient hospitalisations, joint reconstruction surgeries, and emergency outpatient accident treatments resulting from falls, whether caused by an external slip or an underlying illness.
Yes. Under Hong Kong tax legislation, policyholders paying VHIS premiums for eligible dependent relatives—including parents, spouses, and children—can claim an annual Salaries Tax deduction. The deduction ceiling is up to HK$8,000 per insured person for each year of assessment, with no upper limit on the number of qualifying relatives claimed.

© 2026 Bowtie Life Insurance Company Limited. All rights reserved.